6 Common Accounting Mistakes
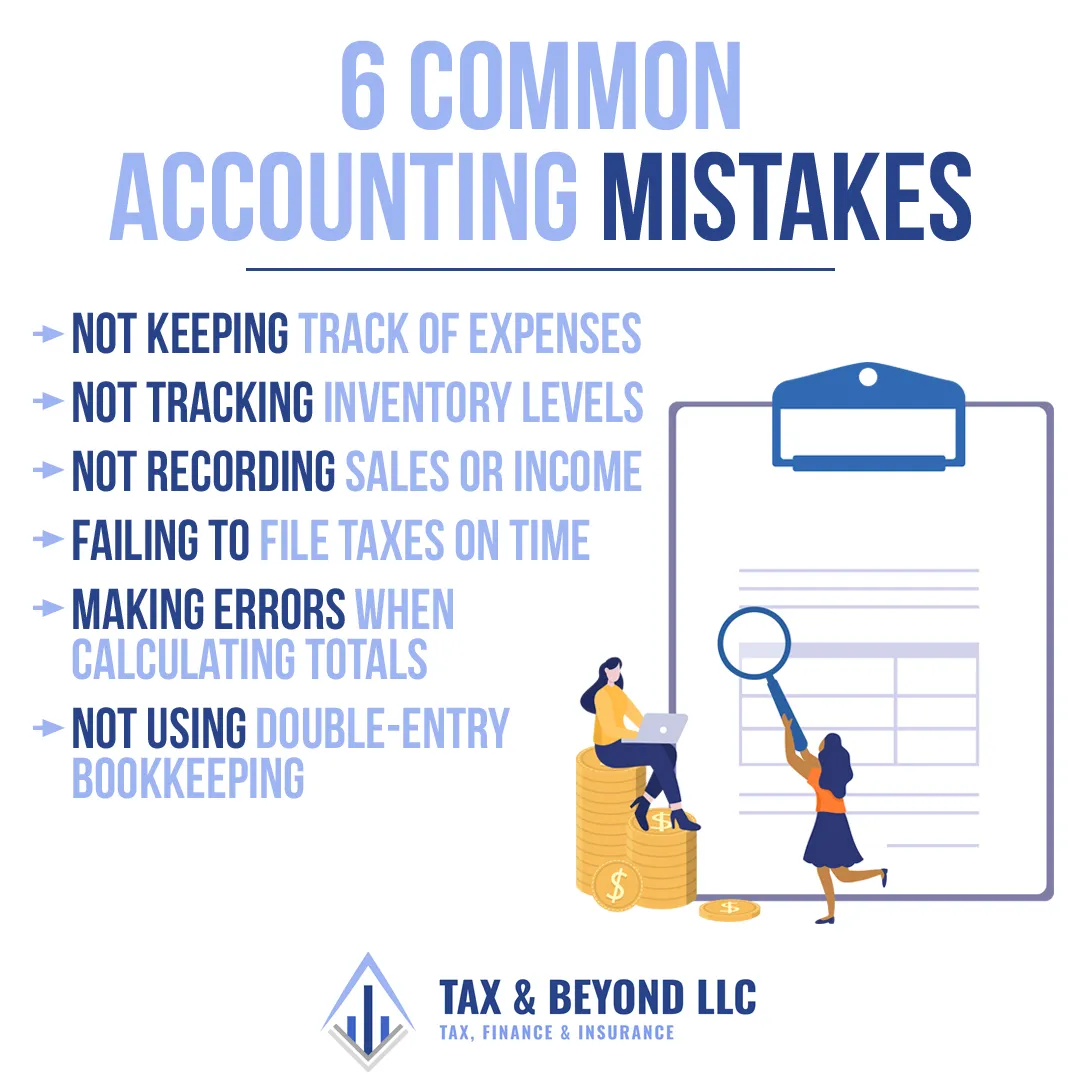
Accurate financial records are crucial for the success of any business. However, accounting can be a complex and challenging task, and mistakes can happen. In this blog post, I will provide you with six common accounting mistakes that businesses make.
- Failing to Keep Accurate Records Keeping accurate financial records is essential for any business. However, many businesses fail to do so, leading to inaccurate financial statements and potential legal and regulatory issues. Ensure that you keep detailed and accurate records of all financial transactions to ensure that your financial statements are accurate.
- Mixing Personal and Business Expenses Mixing personal and business expenses is a common mistake that businesses make. It can lead to inaccurate financial statements and make it challenging to track expenses and income. Ensure that you keep personal and business expenses separate, and use separate bank accounts and credit cards for each.
- Failing to Reconcile Bank Accounts Failing to reconcile bank accounts is another common accounting mistake. Reconciling bank accounts ensures that your financial records match your bank statements and can help you identify errors or fraudulent activity. Ensure that you reconcile your bank accounts regularly to ensure accuracy.
- Not Tracking Expenses Not tracking expenses is another common accounting mistake. Keeping track of expenses is crucial for managing your finances effectively and preparing for tax season. Ensure that you keep accurate records of all expenses, including receipts, invoices, and other documentation.
- Overlooking Depreciation Overlooking depreciation is a common accounting mistake that can lead to inaccurate financial statements. Depreciation is the reduction in value of assets over time, and it is an essential accounting concept. Ensure that you accurately calculate and track depreciation to ensure that your financial statements are accurate.
- Not Planning for Taxes Not planning for taxes is another common accounting mistake that businesses make. Failing to plan for taxes can lead to unexpected tax bills and potential penalties. Ensure that you plan for taxes throughout the year, including setting aside funds for tax payments and working with an accountant to ensure that you are taking advantage of all available deductions and credits.
In conclusion, accounting mistakes can happen, but they can also be prevented. Failing to keep accurate records, mixing personal and business expenses, failing to reconcile bank accounts, not tracking expenses, overlooking depreciation, and not planning for taxes are common accounting mistakes that businesses make. By avoiding these mistakes and working with an accountant, you can ensure that your financial records are accurate and that your business remains in good standing.
🏷️Related Topics
Need Help with Your Taxes?
Our expert tax preparers are here to help you navigate tax season successfully. Get professional assistance and maximize your refund. Contact us today for a consultation.